 how-to
How to Improve Insurance Billing: 7 Steps for Contractors
Table of Contents
- Step 1: Collect Complete Patient and Job Data Before You Start
- Step 2: Improve Insurance Claim Documentation Speed
- Step 3: Reducing Insurance Claim Denials Through Clean Claims
- Step 4: Use Insurance Billing Automation Tools to Cut Manual Work
- Step 5: Improving Adjuster Communication for Faster Approvals
- Step 6: Track Billing KPIs and Run Regular Billing Audits
- Step 7: Build a Patient Financial Experience That Gets You Paid
- Frequently Asked Questions
Last Updated: September 15, 2026
Step 1: Collect Complete Patient and Job Data Before You Start
Learning how to improve insurance billing starts long before a claim is filed. It begins the moment you collect intake data, because incomplete or inaccurate information is the root cause of most downstream denials. In restoration and service contracting, incomplete or inaccurate information is the root cause of most downstream denials. Contractors can lose weeks of reimbursement simply because a policy number was transcribed wrong or a loss date was missing.
Insurance billing is the process of submitting claims to a payer, tracking their status, posting payments, and managing the patient or property-owner portion of the balance until the account reaches zero. Every step depends on clean data at the front end.
What Data to Collect at Intake
Gather these fields before work begins:
- Full insured name, policy number, and claim number
- Date of loss and cause of loss code
- Adjuster name, direct phone, and email
- Property address and mailing address if different
- Deductible amount and any prior claim history
- Scope notes, photos, and signed authorization
A common mistake is treating intake as a formality. In practice, missing adjuster contact details alone can add days to every follow-up call.
Step 2: Improve Insurance Claim Documentation Speed
Documentation speed determines how fast a claim moves. The faster you capture and submit evidence, the shorter your accounts receivable cycle. Many restoration firms now document as they work rather than reconstructing a file days later.
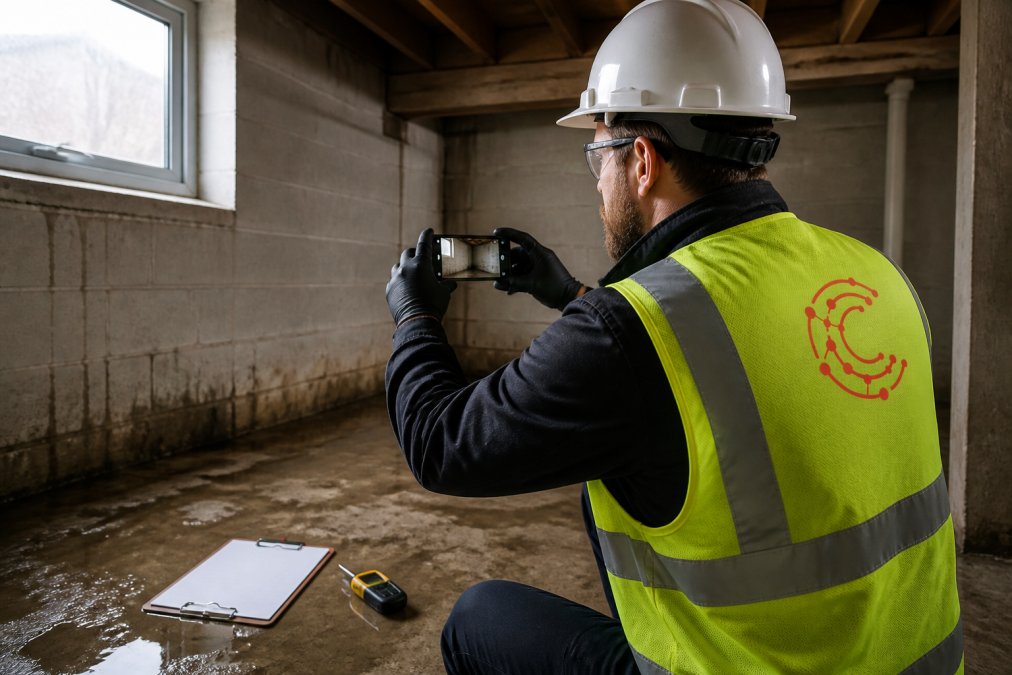
Photo and Video Standards That Adjusters Accept
Adjusters reject files that lack context. Follow these standards:
- Shoot wide, medium, and close-up for every affected area
- Include a moisture meter or measurement reference in frame
- Timestamp and geo-tag photos automatically where possible
- Narrate short videos explaining cause and scope
- Upload same-day, not at project close
What most guides miss is that adjusters process hundreds of files. A clearly labeled, chronological photo set gets approved faster than a perfect set buried in a messy folder.
Step 3: Reducing Insurance Claim Denials Through Clean Claims
Reducing insurance claim denials comes down to one metric: your clean claims rate, or first-pass yield. A clean claim is one that pays without additional information requests. The higher your first-pass yield, the lower your administrative cost per dollar collected.
Common Denial Reasons and How to Fix Them
| Denial Reason | Typical Fix | Impact |
|---|---|---|
| Missing documentation | Same-day photo upload | Fewer rework requests |
| Incorrect policy data | Verify at intake | Fewer rejections |
| Scope mismatch | Itemize line by line | Faster approvals |
| Missed filing deadline | Automated reminders | Preserved reimbursement |
| No prior authorization | Confirm before work | Avoided write-offs |
Denial management is not a back-office chore. It is a front-office discipline.
Step 4: Use Insurance Billing Automation Tools to Cut Manual Work
Insurance billing automation tools remove the repetitive data entry that slows small teams. Instead of retyping policy numbers into a clearinghouse portal, staff push verified data straight from the job record. But automation is not a single switch. It is a sequence, and the order you automate in determines whether you cut work or just move it around.
The Three Layers of Billing Automation
Most platforms bundle features, but the underlying work falls into three layers. Automate them in this order:
- Data capture and validation. Optical character recognition (OCR) and structured intake forms pull policy numbers, dates of loss, and adjuster contacts directly from source documents, then validate them against payer rules before a claim is built. This is the highest-ROI layer because it eliminates the errors that cause most denials.
- Claim assembly and submission. Rules engines map job line items to payer-specific claim formats, attach required documentation, and submit electronically through a clearinghouse. This layer removes the manual re-keying that creates transcription errors.
- Status tracking and follow-up. Automated status queries pull claim status from payer portals on a schedule, flag stalled claims, and trigger follow-up tasks. This layer replaces the spreadsheet-and-calendar approach most small teams use.
What to Look for in a Billing Automation Platform
Prioritize platforms that:
- Convert plain-English job descriptions into structured workflows
- Validate policy and coverage data against payer rules at intake
- Flag budget overruns before they hit your margin
- Draft adjuster responses automatically
- Track claim status across payers in one dashboard
- Produce an audit trail for every claim action
Where AI and Machine Learning Change the Math
Most guides stop at "use automation." The bigger shift is predictive denial management. Machine learning models trained on historical claims can score each claim for denial risk before submission, based on patterns like payer-specific edit rules, procedure-and-diagnosis combinations that historically fail, and missing-data signatures. A high-risk score routes the claim to a human reviewer instead of the payer, which converts a denial into a pre-submission fix.
The practical effect: instead of reacting to denials after they arrive, your team works a short exception queue. A common pattern is that a small share of claims drives most denials, so catching those before submission moves the clean claims rate more than any downstream appeals process.
Cortex by JobDox was built for exactly this. Its AI-native platform drafts adjuster responses and predicts project budgets, so controllers spend less time chasing paperwork and more time on cash flow optimization. The CMS guidance on electronic claims outlines how standardized electronic submission reduces error rates across the industry.
How to Measure Automation ROI
Do not evaluate a platform on features. Evaluate it on four numbers, measured before and after:
- Clean claims rate (first-pass yield)
- Days in accounts receivable
- Administrative cost per claim submitted
- Denial rate by payer
If first-pass yield does not improve within one full billing cycle, the problem is usually upstream data quality, not the tool.
Outsourcing vs. In-House: A Decision Framework
Automation raises a second question most guides skip: should you run billing in-house at all? Use these tests:
- Volume. Below a few hundred claims a month, the fixed cost of a dedicated billing specialist rarely pencils out. Above that, in-house control usually wins on speed and payer relationships.
- Payer mix. A concentrated payer mix with stable rules is easier to automate in-house. A fragmented mix with frequent rule changes favors a vendor that maintains those mappings for you.
- Denial complexity. If denials require clinical or scope expertise to appeal, in-house staff who know the work outperform generalist outsourced teams.
- Data sensitivity. Outsourcing moves protected health information and claim data to a third party, which expands your compliance surface. Weigh that against the vendor's security posture.
A hybrid model is common: keep intake, coding review, and payer relationships in-house, and outsource statement generation and patient collections. That keeps control of the revenue-critical steps while offloading the high-volume, low-judgment work.
Step 5: Improving Adjuster Communication for Faster Approvals
Improving adjuster communication is about rhythm, not volume. Adjusters respond to concise, well-organized updates.
Step 6: Track Billing KPIs and Run Regular Billing Audits
How to Run a Billing Audit That Finds Something
The 5 KPIs That Matter Most
Turn Audit Findings Into Fixes
Secure the Data Your Audits Depend On
Step 7: Build a Patient Financial Experience That Gets You Paid
Frequently Asked Questions
What is the golden rule in insurance billing?
Document everything before you touch anything. In restoration and service contracting, the golden rule is that if it is not documented, it did not happen. Take photos before, during, and after every phase of work. Log moisture readings, equipment placement, and labor hours in real time. When you submit a claim, the adjuster should be able to reconstruct the entire job from your file without calling you. Contractors who follow this rule see fewer claim rejections and faster reimbursement because there is no gap for the payer to question.
What are the most common causes of insurance claim denials for contractors?
The most frequent causes include missing or blurry documentation, incorrect scope codes, work performed before approval, and inconsistent communication with the adjuster. Many denials stem from simple clerical gaps: a missing photo, an unsigned work authorization, or a line item that does not match the approved scope. Reducing insurance claim denials starts with a pre-submission checklist that catches these gaps before the claim leaves your office. Clean claims rates above 90% are achievable when intake, documentation, and submission follow one consistent process.
How can automation improve the accuracy of insurance billing?
Insurance billing automation tools reduce human error by standardizing data entry, flagging missing fields, and generating documentation packages automatically. Instead of an admin manually assembling photos, notes, and invoices, the platform pulls everything into one submission. This cuts the time between project completion and final payment and lowers the chance of a claim rejection due to incomplete paperwork. Automation also creates an audit trail, which matters for compliance and for resolving disputes with payers when they question a line item.
What documentation is essential for faster insurance claim processing?
At minimum, you need dated before-and-after photos, moisture or damage readings, a signed work authorization, itemized scope of work with matching codes, equipment logs, and a final invoice tied to the approved scope. Adding adjuster communication records, change orders, and any carrier correspondence strengthens the file. Contractors who use a standardized documentation checklist report faster approvals because adjusters can verify the claim without follow-up calls. The goal is a complete package on first submission, not a series of back-and-forth emails.