 Ultimate guide
Best Practices for Restoration Job Costing
Last Updated: November 4, 2026
Quick Summary
Effective restoration job costing requires tagging every labor hour, equipment day, material draw, and subcontractor invoice to a specific job and phase as it happens. Split direct from indirect costs, use burdened labor and standard equipment rates, and reconcile your job cost ledger against the carrier's estimate line by line before closeout.
- Split every expense into direct job costs and indirect overhead before tracking anything else.
- Build a burdened labor rate from base wage plus taxes, workers' comp, benefits, insurance, and paid time off.
- Break every job into phases and tag each cost to a phase at the point of entry.
- Map every cost code to a line item on the carrier's estimate and track approved versus incurred by line.
- Review estimated versus actual cost by phase after every job and rank closed jobs by margin monthly.
Table of Contents
- Why Restoration Job Costing Fails Without Real Job-Level Data
- Direct vs. Indirect Costs: Building Your Restoration Cost Categories
- Phased Cost Tracking From Mitigation to Reconstruction
- Improving Insurance Claim Documentation Speed to Protect Margins
- Change Orders, Purchase Orders, and Standardized Coding
- Restoration Job Costing Software: What to Look For
- Construction Job Costing Templates and When They Fall Short
- Post-Job Profitability Analysis and Common Costing Mistakes
- Frequently Asked Questions
Why Restoration Job Costing Fails Without Real Job-Level Data
Most restoration companies can tell you what they billed last month. That gap is where restoration job costing breaks down, and it is the reason so many contractors feel busy but not profitable. Why restoration businesses fail to track overhead explains how that breakdown happens and how to prevent it.
The core problem is that restoration work generates costs across multiple phases, multiple trades, and multiple approval cycles, often before a single dollar lands.
Real job-level data means every labor hour, equipment day, material draw, and subcontractor invoice is tagged to a specific job and phase as it happens.
Projul's 2026 job costing guide makes a related point: using real cost data from past jobs is what tightens future estimates and surfaces budget overruns by the second week of a project rather than at closeout.
Direct vs. Indirect Costs: Building Your Restoration Cost Categories
Restoration job costing only works when your cost categories match how restoration work actually spends money.
The most common mistake is letting indirect costs drift into direct job budgets, which makes every job look less profitable than it is.
For a practical breakdown of turning these categories into a margin calculation, see our guide on how to calculate gross profit margin on restoration jobs.
Calculating a Burdened Labor Rate
A burdened labor rate is the true hourly cost of a technician: base wage plus payroll taxes, workers' compensation, benefits, insurance, and paid time off. Bidding from base wage is the fastest way to lose money on labor.
Build the rate once, review it quarterly, and use it everywhere: estimates, change orders, and post-job analysis. For the full method, see how to recover restoration overhead and profit.
Equipment Rates and Overhead Allocation
Charge equipment to jobs at a standard internal rate rather than actual ownership cost. Deltek's 2026 construction job costing guidance recommends exactly this approach for accurate project-specific profitability tracking, per Deltek's construction job costing resources.
Allocate overhead with a consistent driver, such as direct labor hours or direct job cost, and apply the same driver to every job. Consistency matters more than precision here.
Phased Cost Tracking From Mitigation to Reconstruction
Restoration jobs move through distinct phases with different cost behavior. Mitigation is labor- and equipment-heavy with tight timelines. Reconstruction is materials- and subcontractor-heavy with longer schedules.
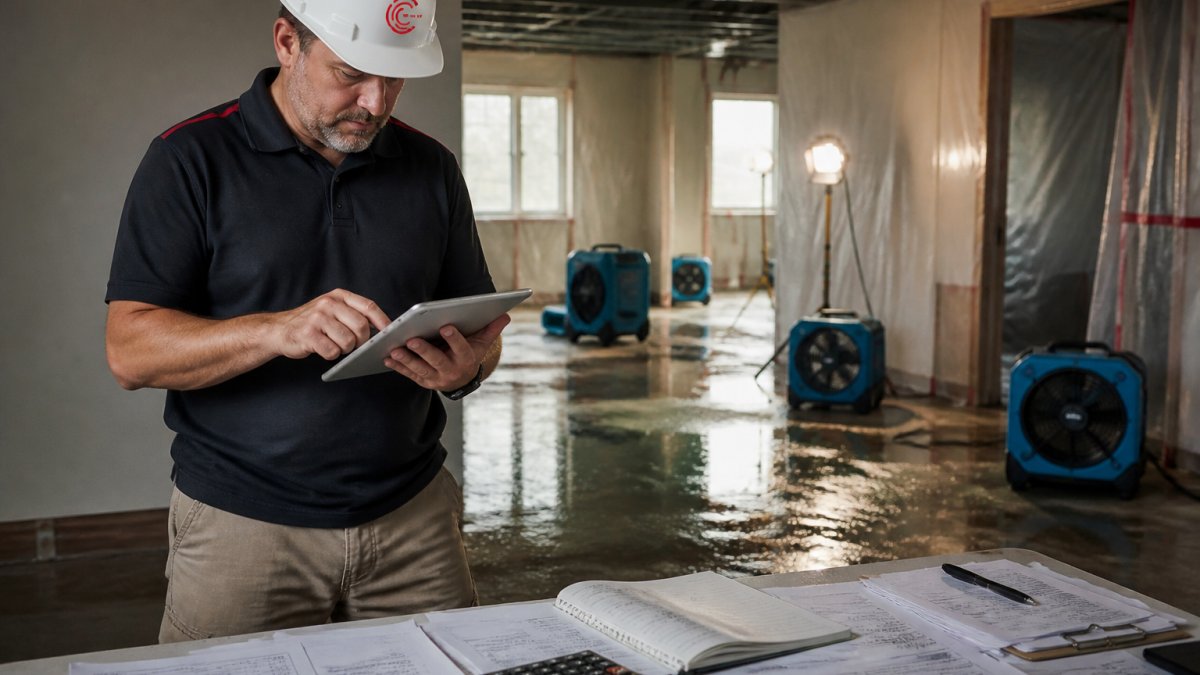
Break every job into phases: emergency response, water extraction, structural drying, demolition, remediation, contents handling, and reconstruction. Tag every cost to a phase at the point of entry.
Work-in-progress reporting belongs here too. WIP reports need to be timely and connected to field-level decisions, not filed away as an accounting artifact, per ABC East PA's 2026 job costing guidance.
Improving Insurance Claim Documentation Speed to Protect Margins
Documentation speed is a costing issue, not an administrative one.
Restoration is an insurance-billed business, and that changes the costing model. Your job cost ledger and the adjuster's estimate are two separate documents that must be tied together.
Build the reconciliation into the job, not after it:
- Map every cost code to a line item on the carrier's estimate. Your extraction labor, drying equipment days, antimicrobial, demolition, and reconstruction lines should each have a matching estimate line and an approved quantity. If a cost has no estimate line, it is either a change order or an unbilled item, and both need to be flagged the day they occur.
- Track approved versus incurred by line, not by job total. A job can look profitable in total while one line (often drying equipment days or contents handling) is running at a loss that the carrier will never pay for. Line-level variance is where the money hides.
- Log every adjuster communication with dates, outcomes, and the cost impact. A verbal approval for two extra drying days is not revenue until it is written into a supplement. Record the date, the adjuster's name, what was approved, and the dollar amount, and attach it to the job and phase.
A common pattern is the office reconstructing documentation after the fact, which is where scope items get dropped and never billed.
For a step-by-step workflow, read our guide on speeding up insurance claim documentation.
Change Orders, Purchase Orders, and Standardized Coding
Change orders and purchase orders are where restoration margins quietly leak.
Treat every change order as a costing event, not a paperwork event. That means five things happen every time:
- Assign it a number and tie it to the original job and phase. A change order without a phase tag cannot be compared to the estimate line it modifies.
- Record the cost against it as the cost is incurred. Labor hours, equipment days, and materials that belong to the change order should be coded to the change order, not folded into the base job. If they are folded in, the base job looks over budget and the change order looks free.
- Get written approval before the work proceeds, or document why you could not. Emergency mitigation often cannot wait for a signature. In that case, record the verbal approval with date, adjuster name, scope, and dollar amount, and submit the written supplement the same week.
- Price the change order from your burdened labor rate and standard equipment rate, not from base wage. A change order priced at base wage loses money on every hour, and it is the most common pricing error in restoration supplements.
- Reconcile the change order against the final carrier payment. An approved change order that was never paid is a receivable, not revenue, and it needs to be tracked as such.
Purchase orders work the same way: issue them before the spend, not after the invoice arrives, and match every invoice to a PO before it hits the job.
Standardized coding holds the system together. Build a consistent code list for cost types, phases, and job numbers, and require every entry to carry all three.
Restoration Job Costing Software: What to Look For
Restoration job costing software should do three things: capture costs at the job and phase level as they happen, connect documentation to those costs, and surface overruns while there is still time to act. Most generic accounting tools handle the first poorly and the second not at all. To compare options against these criteria, see the best software for managing contractor job costs.
Evaluate any platform against these criteria:
| Criterion | What Good Looks Like | Why It Matters |
|---|---|---|
| Job and phase tagging | Required field on every cost entry | Enables phased tracking and variance analysis |
| Documentation capture | Photos and notes tied to job and phase | Speeds claim submission, protects scope |
| Budget vs. actual visibility | Real-time, field-accessible | Catches overruns early, not at closeout |
| Change order tracking | Numbered, approved, cost-linked | Prevents unbilled scope |
| Reporting | Job-level profitability and WIP | Supports bidding accuracy and cash flow |
Cortex by JobDox was built for this specific problem. The platform predicts project budgets and flags overruns early, drafts adjuster responses to help recover more money, and answers job, crew, and financial questions in plain English through Cortex Copilot. Setup is automated from plain-English descriptions of how you work. You can start a 14-day free trial to evaluate it for your own jobs.
Construction Job Costing Templates and When They Fall Short
Construction job costing templates are a reasonable starting point and a poor long-term answer. A spreadsheet can hold cost categories, phase columns, and a budget-versus-actual row, and for a two-person operation that may be enough.
Templates fall short in four predictable places:
- Data entry lag. Costs land in the sheet days after they were incurred, so the sheet always describes the past.
- No documentation link. Photos and adjuster notes live in email and camera rolls, disconnected from the numbers.
- Version drift. Multiple copies circulate, and nobody knows which one is current.
- No change order discipline. Rows get added without approval trails.
Use a template to define your categories and codes. Move off it when you have more than a handful of active jobs, because at that point the manual entry cost exceeds the value of the visibility.
Post-Job Profitability Analysis and Common Costing Mistakes
Post-job analysis is the step almost everyone skips, and it is where the compounding value sits.
Run this review monthly across all closed jobs and rank them from best to worst margin.
The mistakes that show up most often:
- Bidding labor at base wage instead of a burdened labor rate
- Never allocating overhead, so every job looks profitable
- Tracking costs by job but not by phase
Watch out: if your job costing only produces a monthly total, you cannot separate a good month from a lucky one, and the next bid will be built on a guess.
Frequently Asked Questions
What are the 7 steps involved in job costing?
The seven steps are: estimate the job from the scope of loss, set up a job code and budget, assign direct costs (labor, materials, equipment), allocate indirect expenses and overhead, track costs as work progresses in phases, compare actuals against the estimate with variance analysis, and close out with a post-job profitability review. Each step feeds the next, and skipping the post-job review is where most restoration contractors lose the feedback loop that tightens future bids.
How do you calculate job costing for restoration projects?
Start with the scope of loss and build a line-item budget. Apply a burdened labor rate that includes payroll taxes, workers' comp, and benefits rather than the base wage. Charge a standard rental rate for drying equipment and air movers instead of actual ownership costs. Add overhead as a percentage, then track every expense against the job code weekly. Compare actual to estimated at each phase so overruns surface by week two, not at closeout.
What is the difference between direct and indirect costs in restoration?
Direct costs attach to a specific job: extraction labor, antimicrobials, drywall, and equipment days on site. Indirect expenses, such as office rent, estimator salaries, vehicle insurance, and marketing, keep the business running but serve every job. Indirect costs must be allocated across jobs through an overhead rate, or your profit margin will look healthier than it is. Omitting overhead is one of the most common causes of under-billing.
How can restoration job costing software improve accuracy?
Restoration job costing software connects field data to the ledger in real time. Crew hours, equipment logs, and material receipts post against the job code as they happen, so work-in-progress reports reflect reality. AI-driven platforms can also flag a project budget drifting past its estimate early, draft adjuster responses with supporting documentation, and shorten the gap between completed work and invoicing, which improves cash flow management.
Why is real-time job costing critical for insurance claim approval?
Adjusters approve what they can verify. When costs are tracked as they occur, you can attach dated photos, equipment logs, and moisture readings to each line item the moment a question comes up. That speeds documentation and reduces back-and-forth. Delayed costing means evidence gets reconstructed from memory weeks later, which weakens change order requests and often results in approved amounts that fall short of actual mitigation costs.
What are common mistakes that lead to under-billing in restoration?
The biggest culprits: leaving overhead and profit out of the estimate, using base wages instead of a burdened labor rate, forgetting equipment days after drying is complete, and failing to track change orders for scope added mid-job. Another frequent error is closing jobs without a variance analysis, so the same underestimate repeats on the next loss. Standardized coding and phased tracking catch each of these before the invoice goes out.
Restoration job costing rewards contractors who close the loop between field documentation, job-level cost capture, and post-job review. That loop is exactly what Cortex by JobDox is built to run: it predicts project budgets and flags overruns early, automates documentation and operational workflows, and drafts adjuster responses to help you recover more of what you earned. Start your 14-day free trial and see what your jobs actually look like at the job level.